How to Lower Car Insurance Rates Without Downgrading Your Coverage
Written and reviewed by the CarCultureHQ Editorial Team. See our Editorial Policy for sourcing and corrections.
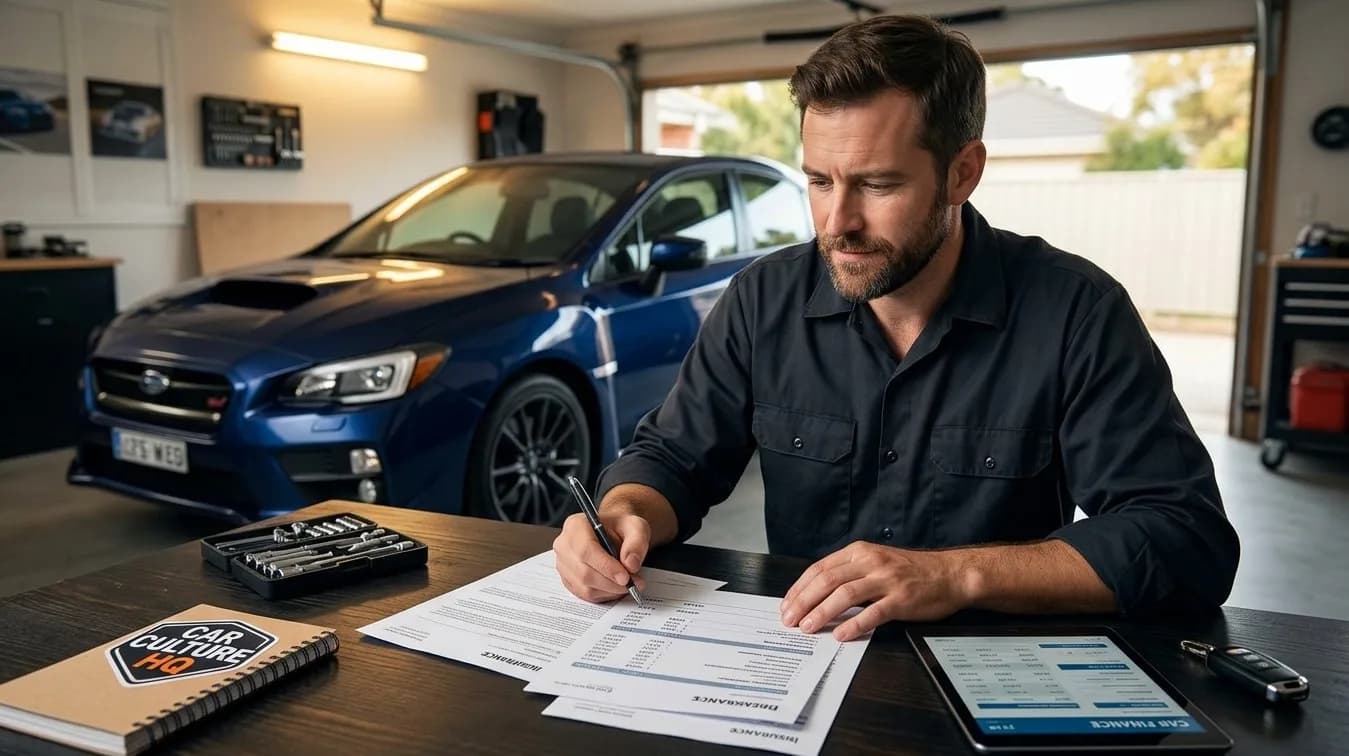
Summary: Most drivers treat auto insurance like a fixed utility bill: pay it every month, complain when the rate goes up, and never look under the hood of the policy. That passive approach costs you money. Insurance companies rely on consumer inertia, quietly creeping rates up every renewal cycle. By understanding how underwriters price risk, auditing your actual mileage, and matching your policy structure to how you actually drive, you can lower car insurance rates significantly without gutting the safety net you bought insurance for in the first place.
The Hidden Penalty of Insurance Loyalty
Here is something the slick television commercials never mention: being a loyal customer often costs you more money.
Insurance underwriters use a pricing strategy known as price optimization. In plain English, algorithms track how likely you are to switch providers when your rate goes up. If you have been with the same carrier for five years without complaining, the system flags you as low risk for leaving. Your rates creep up 5% or 8% every renewal cycle, even if your driving record stays spotless.
The fix is straightforward. Treat your insurance policy like an active contract, not a lifetime subscription. Re-evaluating your coverage every 18 to 24 months puts you back in control.
Join CarCultureHQ
Claim your free digital garage
Build your ride profile, log modifications, join a crew, and get your build in front of thousands of enthusiasts.
Create your free garage5 Practical Steps to Lower Your Premium Right Now
POLICY AUDIT CHECKLIST | |
|---|---|
1. Audit Mileage | Adjust reported annual mileage to reflect real driving habits, remote work, or short commutes. |
2. Rebalance Deductibles | Raise collision deductibles while holding comprehensive deductibles lower if needed. |
3. Cut Duplicates | Drop tow packages or rental add-ons covered elsewhere (AAA, credit cards, manufacturer warranties). |
4. Update Status | Notify carriers of garage changes, marriage, or professional affiliation discounts. |
5. Shop the Market | Collect 3 quotes every 18-24 months using your exact current declaration page settings. |
1. Fix Your Reported Annual Mileage
When you opened your policy, the representative probably assigned you a standard 12,000 or 15,000 annual mileage figure. If you started working from home three days a week or moved closer to your job, that number is plain wrong.
Log into your portal or check your policy declaration page today. If you are driving 6,500 miles annually instead of 12,000, call your carrier. Dropping your mileage tier can lower car insurance rates by 5% to 15% immediately.
2. Rebalance Collision and Comprehensive Deductibles
Many drivers assume deductibles must match. They set both collision and comprehensive at $500 and leave them there.
That is usually a mistake. Collision coverage (hitting another car, a pole, or a guardrail) makes up the bulk of your premium cost. Raising your collision deductible from $500 to $1,000 cuts that portion of your bill noticeably. Meanwhile, comprehensive coverage (storm damage, deer strikes, broken glass) is relatively cheap. You can keep comprehensive at $250 or $500 to protect against unavoidable surprises while saving on collision.
3. Eliminate Add-On Features You Already Pay For Elsewhere
Look at the itemized line items on your declaration page. You will often spot micro-charges adding $5 to $15 a month per car:
Roadside Assistance: If you carry a AAA membership, drive a newer vehicle with factory roadside coverage, or use a premium credit card, you are paying twice for the same service.
Rental Car Reimbursement: Useful if your car is your sole daily driver, but if you have a second household car or can work remotely during repairs, skip it.
Custom Equipment Coverage: Unless you have modified wheels, aftermarket suspension, or audio gear, cancel unnecessary custom parts riders.
4. Optimize Your Payment Structure
How you pay matters almost as much as what you buy. Most carriers charge a $3 to $7 processing fee every time they bill you monthly.
If you set up automatic ACH payments from a bank account instead of paying by credit card manually each month, carriers usually waive administrative fees. If you can afford to pay the 6-month or 12-month term upfront, you can trigger an additional paid-in-full discount ranging from 5% to 10%.
When to Keep Your Coverage High
Cutting costs makes sense, but cutting essential liability protection is dangerous. The goal is to lower your bill without destroying your financial security.
Never drop state liability limits down to the legal minimum just to save twenty dollars a month. State minimums (like 25/50/25 in many regions) were created decades ago. In an era where the average new vehicle costs over $45,000, causing a minor multi-car accident can easily exceed minimum limits, leaving your personal savings and wages exposed to lawsuits.
Keep your bodily injury and property damage liability limits at $100,000/$300,000/$100,000 at a minimum, or carry an overarching umbrella policy if you own a home or substantial assets. Cut the fluff in the policy, not the core shield.
How to Shop Your Policy in 30 Minutes
Shopping for insurance sounds tedious, but it does not require hours of phone calls if you do it strategically:
Pull Your Current Declaration Page: This document shows your exact coverage limits, deductibles, and VIN numbers.
Use Identical Metrics for Quotes: When getting quotes from alternative carriers, input the exact same liability limits and deductibles you currently hold. Comparing a high-deductible quote from Brand A to a low-deductible policy from Brand B tells you nothing useful.
Check for Group and Affiliation Discounts: Alumnae associations, union memberships, engineering or trade credentials, and credit unions routinely have negotiated group rates with specific carriers.
Compare Independent Brokers with Direct Insurers: Get a quote from a direct-to-consumer carrier online, but also call a local independent agent who represents multiple regional companies. Regional carriers often beat national brands on rate stability.
Take Back Control of Your Auto Expense
Lowering your car insurance rates isn't about compromising your safety or taking foolish risks with liability. It comes down to stripping away corporate markup, clearing out duplicate services, and making sure your policy accurately reflects how you live and drive today.
Take thirty minutes this week to pull your declaration page, check your mileage, and run three apples-to-apples quotes. You will likely find a few hundred dollars hiding in plain sight.
Join CarCultureHQ
Claim your free digital garage
Build your ride profile, log modifications, join a crew, and get your build in front of thousands of enthusiasts.
Create your free garageFrequently asked questions
Will checking new car insurance quotes hurt my credit score?
No. Insurance companies perform a soft credit inquiry when generating quotes. Soft pulls do not impact your credit score or show up on consumer credit reports viewed by lenders.
Is telematics (drive-tracking apps or OBD plugs) worth using?
It depends on how and when you drive. If you log low mileage, avoid hard braking, and rarely drive between 12 AM and 5 AM, telematics programs can unlock discounts between 10% and 30%. However, if you have a heavy foot, commute late at night, or drive in dense stop-and-go traffic, some carriers may actually raise your rate based on that data.
How much can I lower my car insurance rate by bundling home or renters insurance?
Bundling auto insurance with a home, condo, or renters policy is usually one of the largest available discounts, often saving between 10% and 25% across both policies combined. Always verify that the combined total is lower, not just the auto portion.
Should I drop collision and comprehensive coverage on an older car?
A common rule of thumb: if the annual cost of comprehensive and collision coverage exceeds 10% of your vehicle's total market value, consider dropping those coverages. For example, if your older sedan is worth $3,000 and physical damage coverage costs $400 per year with a $1,000 deductible, you are paying relative overage for minimal net payout in a total loss.

Comments
Join the conversation on How to Lower Car Insurance Rates Without Downgrading Your Coverage. Keep it civil — admins moderate reports.
Loading comments…